ENOperational riskRegulationBasel IIILatin America
How quantitative is operational risk supervision in Latin America?
By Fernando Hernández · October 20, 2026 · 7 pages
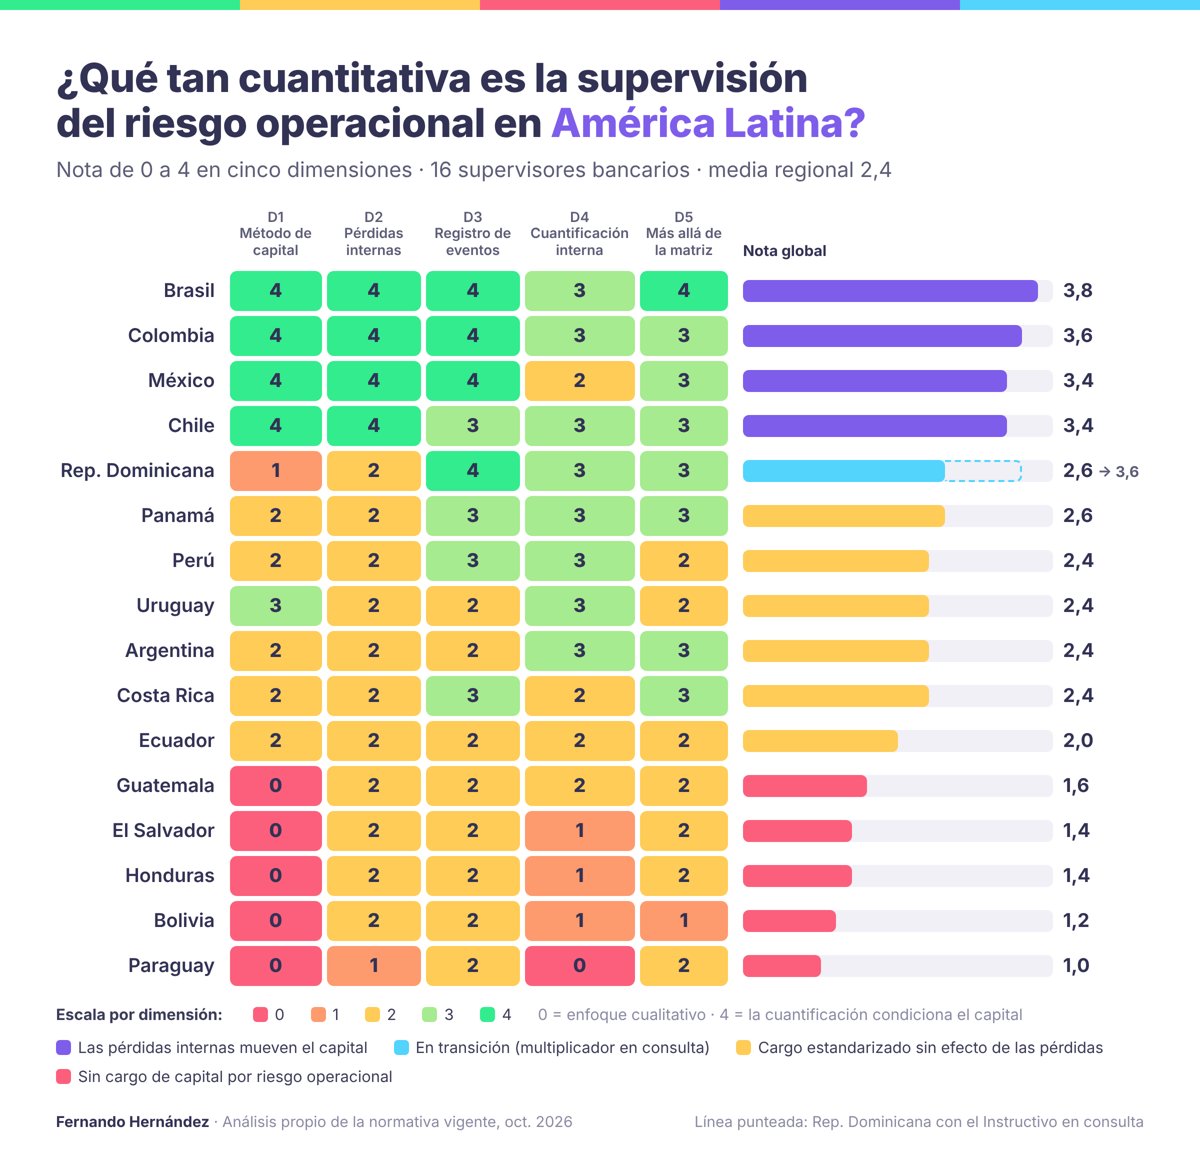
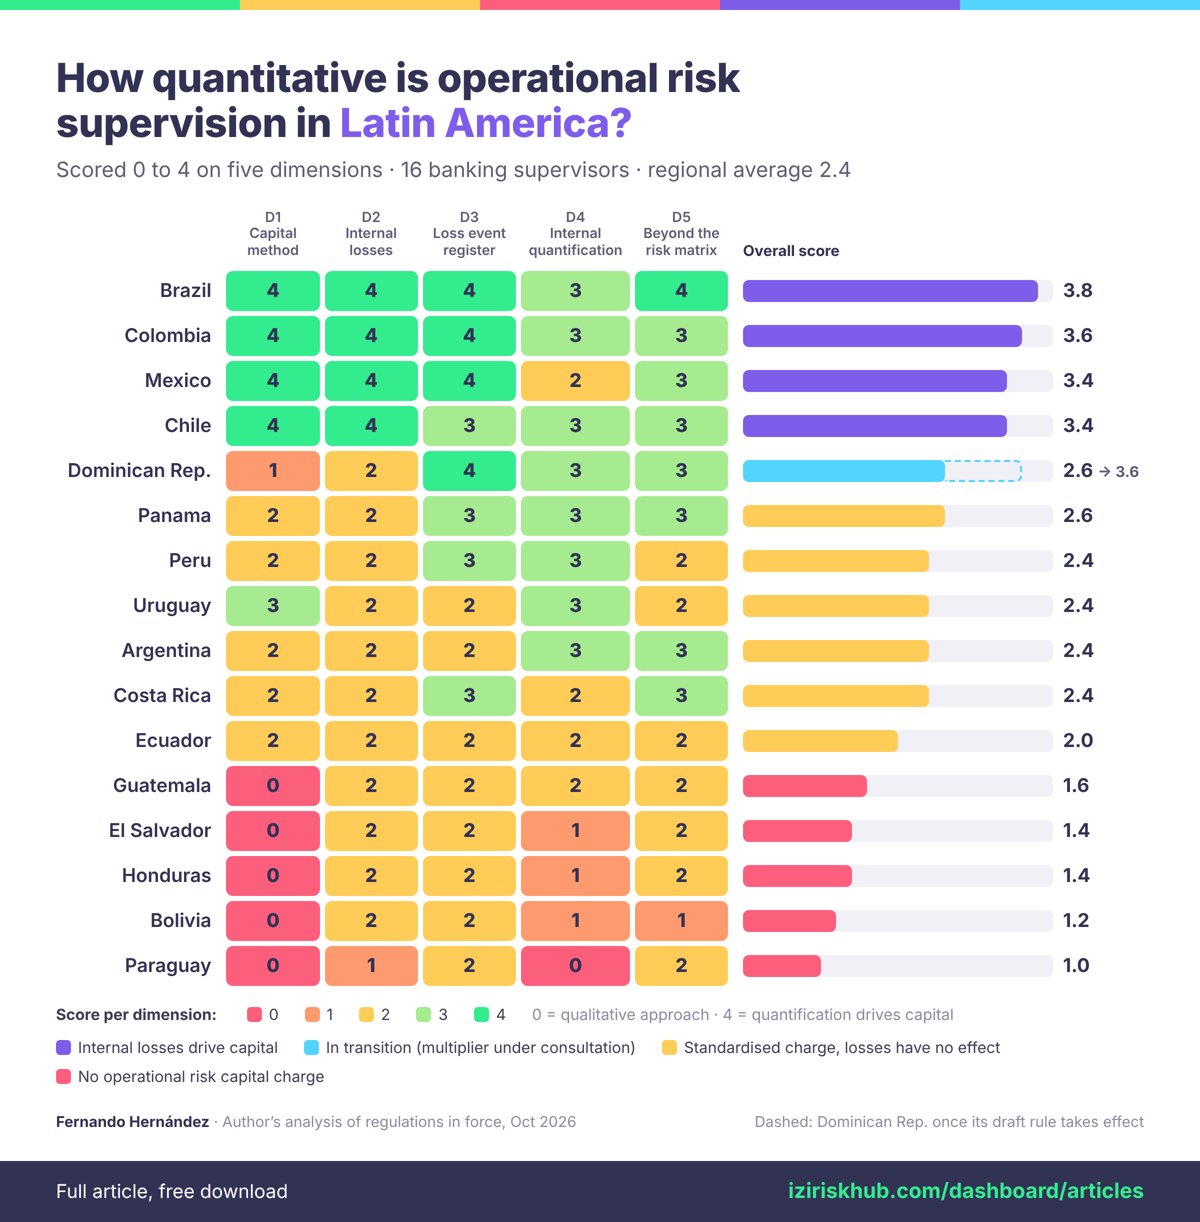
A comparison of 16 banking supervisors on five dimensions: capital method, use of internal losses, loss event register, internal quantification and reliance on risk matrices. Only Brazil, Colombia, Mexico and Chile currently tie capital to loss history; no supervisor requires Monte Carlo for regulatory capital.